Most Nigerians view loans, and debt in general, as a shameful thing. There is a stigma around people who borrow, so most people shy away from formal lending and turn to friends and family for help instead.
One reason for this stigma is that many people have taken loans they could not afford and struggled to pay back. Additionally, some take loans from unlicensed lenders who resort to public shaming to recover the unpaid debt. Naturally, most Nigerians want to avoid such a poor experience, so they avoid loans in general.
However, debt can help with emergencies and raise capital for genuine opportunities. In cases of medical emergencies, a quick loan from a reputable lender can be life-saving. Entrepreneurs have also used business loans to grow multinational companies.
This article will answer:
- Should I take a loan?
- When not to take a loan.
- Red flags to look out for in loan apps.
- The best place to get an instant loan in minutes in 2026.
How to Know When to Take a Loan
Borrowing is not inherently good or bad. It depends entirely on what the money is for and whether you have thought it through properly.
Dr Emeka Ucheaga, Head of Strategy, Research and Financial Inclusion at Credit Direct, puts it plainly: “Productive credit is a powerful tool for driving wealth creation because it enables an individual to access credit to buy assets or fund business activities that generate income. If the potential return from the investment or acquisition exceeds the cost of borrowing, it is a good idea to leverage productive credit.”
But he attaches firm conditions. “You must be careful and pay attention to risk, because expected income can differ from actual income after investment.” His guardrails: do your due diligence, minimise risk wherever possible, and “avoid overleveraging by borrowing far beyond what you can comfortably repay if risk crystallises.”
For anyone weighing whether to borrow at all, he offers three questions to ask first: Do I actually need this credit, or is it a want? Can I afford the terms? And how exactly will I repay it? “Pick loan tenors that match your cash flow, so the duration allows you to repay comfortably.” For business owners, the rule is simpler still: “ensure that the cost of credit is lower than the potential ROI before taking it.”
With that framework in mind, here are the situations where taking a loan actually makes sense.
A genuine emergency.
A medical emergency, an urgent repair, or any situation where waiting could cost you more than the loan itself, whether in money, health, or safety. This is the clearest case for borrowing: the need is real, time-sensitive, and cannot wait for savings to catch up.
A real opportunity.
A business opportunity whose expected return outpaces the loan's interest is exactly the kind of “productive credit” Dr Emeka describes. If a ₦500,000 loan lets you fulfil an order worth ₦2 million in profit, the loan is not a burden; it is what made the opportunity possible.
Urgent needs.
Rent and school fees fall into a category of their own. They are not emergencies in the medical sense, but they are non-negotiable and time-bound. A loan that bridges a temporary shortfall for either is a reasonable use of credit, especially when the alternative is defaulting on an obligation with real consequences.
Wants, within reason.
Not every loan needs to be tied to a crisis or an income-generating opportunity. Sometimes it is a new oven that saves you hours every week, or a car that changes how reliably you get to work. Buy Now Pay Later products, like Credit Direct Checkout, exist for exactly this kind of borrowing, letting you spread the cost of something that genuinely improves your life. The caveat is important: you must be able to afford the repayments comfortably, without straining your finances elsewhere. A want is only a reasonable loan when it does not become a source of stress.
When You Shouldn’t Take a Loan
Just as there are good reasons to borrow, there are situations where taking a loan is almost always a mistake.
For family celebrations.
Weddings, naming ceremonies, and other family events carry enormous social pressure in Nigeria to spend big. But going into debt to fund a party is borrowing against your future for a single day. The celebration ends. The repayment does not.
To impress people.
If the real reason for a loan is how it will look to others rather than what it does for you, that is a warning sign. The irony is that when the debt becomes unsustainable, it will lead to more public ridicule and shame.
For vacations or trips.
A holiday is a want, not a need, and it produces no return that can help you repay the loan. If you cannot afford a trip from your savings, the more disciplined path is to save toward it, not borrow for it.
When you have other debt obligations.
Taking on a new loan while you are still struggling to service an existing one rarely ends well. It usually means covering one debt with another, which compounds your financial pressure rather than relieving it. Before borrowing again, get a clear picture of your existing obligations first.
Read: What Happens If You Don’t Pay Your Loans
Red Flags to Look Out for in Loan Apps
Not every lender has your best interests at heart. Here is what to watch for before you borrow from any app.
Unclear rates.
A trustworthy lender shows you the total cost of borrowing, your interest rate, and your full repayment schedule before you accept anything. If an app is vague about what you will actually pay, or the numbers only become clear after you have committed, walk away.
Aggressive marketing.
Be wary of any lender that pressures you to borrow urgently or relies on testimonials and reviews that sound too good to be true. A legitimate lender does not need to rush you into a decision.
Bad collection practices.
Some unlicensed lenders resort to public shaming, contacting your phone contacts, or harassment when a payment is late. If a lender’s approach to a missed payment involves humiliation rather than a conversation, that tells you everything you need to know about how they view you as a customer.
Read: How To Pick The Right Loan App
The Best Place to Get an Instant Loan in Minutes in 2026
If you have weighed your reasons, avoided the red flags, and decided that a loan is the right move, where you borrow from matters just as much as why.
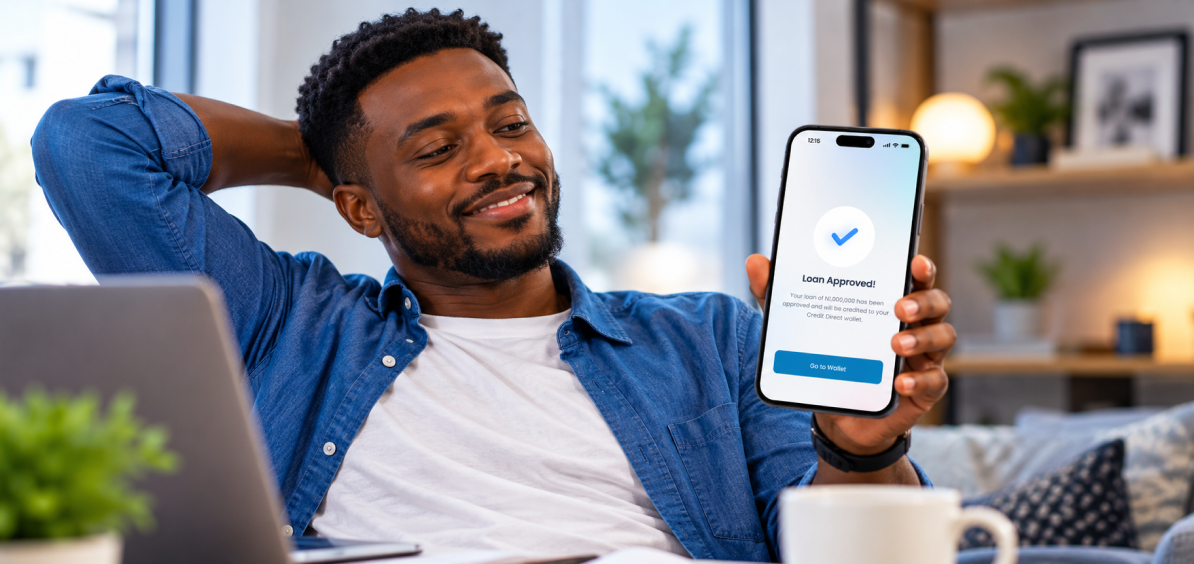
The Credit Direct App is built for exactly this moment. It lets you apply for a loan of up to ₦5 million directly from your phone, with no paperwork, no branch visits, and no days of waiting for a decision.
Before you accept any offer, the app shows you your full loan amount, repayment schedule, total interest, and total repayable amount, so you know exactly what you are agreeing to.
Credit Direct is a CBN-licensed finance company and part of the FCMB Group, with close to two decades of lending experience in Nigeria. There is no harassment, no shaming, and no unclear terms, just a straightforward, transparent way to borrow when borrowing genuinely makes sense.