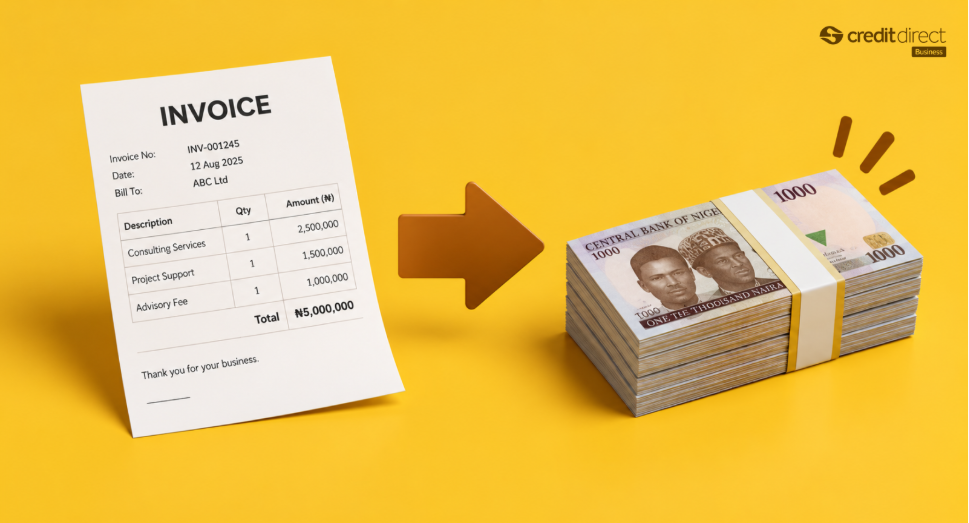
If your business delivers goods or services to a buyer on 60- to 90-day payment terms, you do not have to wait that long to get paid. Invoice discounting, sometimes called AR Factoring, lets you unlock the cash tied up in an accepted invoice within a day or two, using the invoice itself instead of collateral. For Nigerian manufacturers and B2B suppliers, this turns a fixed 90-day wait into working capital you can use immediately, without taking on new debt just to bridge the gap.
Extended payment terms are simply part of doing business with large buyers. A distributor, a retailer, or a corporate client agrees to pay in 60, 75, or 90 days, meanwhile you have already paid for raw materials, labour, and logistics to fulfil the order. The result is a business that looks profitable on paper but runs short on cash in practice, order after order.
The Real Cost of Waiting on Long Payment Terms
A 90-day payment term does not just delay income. It delays everything downstream of it. You cannot restock for the next order until this one pays. You cannot take on a bigger contract without worrying whether you will have cash to deliver it. And if a cash crunch forces you to borrow at short notice instead of planning ahead, you often end up paying more for that emergency funding than you would have for financing the invoice itself from day one.
So Fresh CEO, Olagoke Balogun, shared this perspective in The Cashflow Framework for Business Owners:
I can tell you for free. Cash in your business gives you peace of mind. It allows you to sleep well at night and wake up the next day knowing that you have what it takes to continue operating and running your business.
This is the core problem invoice discounting solves. Instead of waiting on your buyer's calendar, you get paid on your own.
Invoice Discounting VS AR Factoring
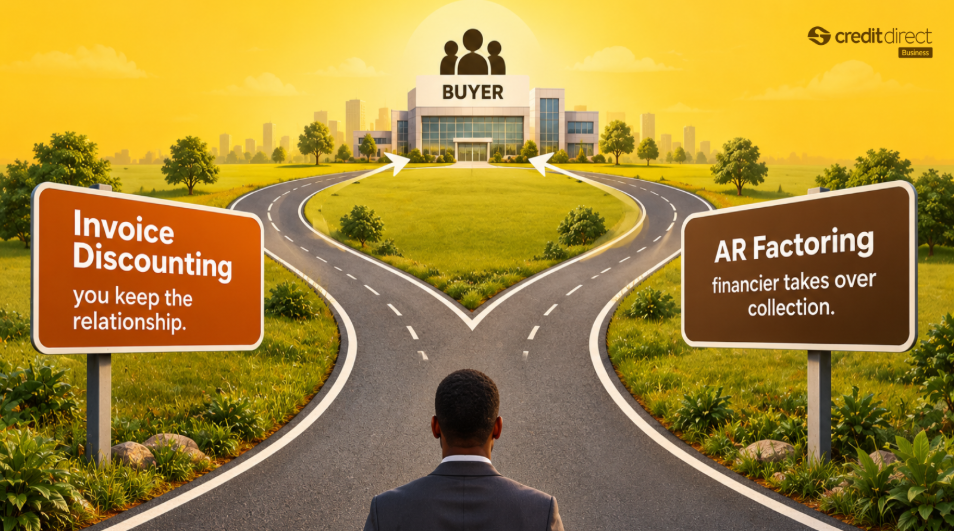
Invoice discounting and AR factoring both do the same basic job: they turn an invoice you have already earned into cash you can use today. The difference is who manages the relationship with your buyer afterward. With factoring, the financier often takes over collection directly. With invoice discounting, you keep managing your buyer relationship as usual, and the financier is repaid once your buyer settles the invoice through a domiciled account. In the Nigerian market, the two terms are frequently used interchangeably, but it is worth knowing which structure you are actually being offered.
Credit Direct Business offers Invoice Discounting, built specifically for businesses working with buyers on extended payment terms. You submit your accepted invoice and a buyer domiciliation letter, and funds are released to your business wallet well ahead of the invoice's original due date.
What It Actually Costs
Financing an invoice is not free, but it is priced to be cheaper than the cost of a cash shortage. Credit Direct Business's Invoice Discounting has no key man insurance charge on it.
Your exact offer still depends on your credit assessment and the value of the invoice, so confirm the final figures on your Loan Agreement Form before accepting.
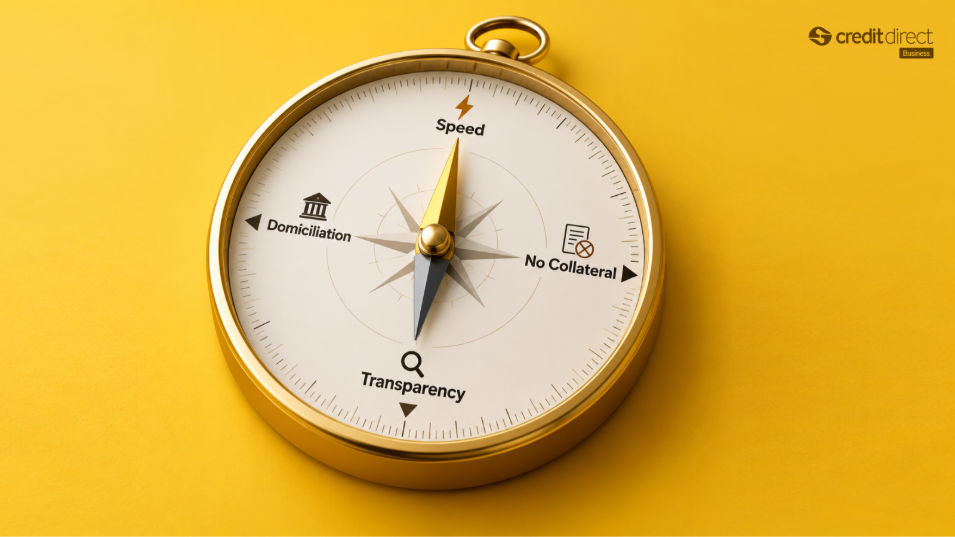
What to Look for in a Same-Day Invoice Provider
- Speed: a same-day or one- to two-day turnaround from a complete application, not a multi-week process.
- No traditional collateral: the accepted invoice and buyer domiciliation should be enough. If a provider still asks for a fixed asset as security, that defeats the purpose.
- A clear domiciliation process: your buyer's payment should be routed transparently, without disrupting the underlying business relationship.
- Transparent, flat fees: know the interest rate and the management fee upfront, so you can compare the real cost against waiting it out.
Credit Direct Business's Invoice Discounting facility is built around exactly these points, which is why it fits manufacturers and suppliers dealing with long payment terms as a standing need, not a one-off emergency.
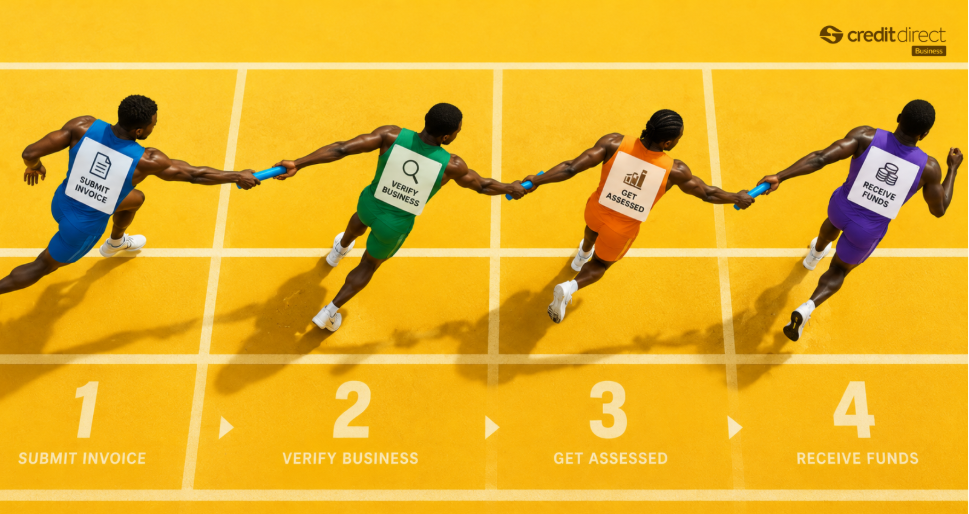
How to Get Paid Early on an Invoice
- Submit your accepted invoice along with a buyer domiciliation letter.
- Verify your business with your CAC certificate, director ID and BVN, and twelve months of bank statements.
- Get assessed. Our team reviews the invoice and your business profile.
- Receive funds in your business wallet, well ahead of the invoice's due date, while your buyer still pays on the original schedule.
Frequently Asked Questions
What is the difference between invoice discounting and AR factoring?
Both advance cash against an unpaid invoice. Invoice discounting lets you keep managing your buyer relationship directly, while factoring often hands collection over to the financier. Many Nigerian lenders use the terms loosely, so always confirm which structure applies.
How fast can I get paid on an invoice in Nigeria?
With a complete application and accepted invoice, funds can be released to your business wallet within 24 to 48 hours.
What are typical invoice factoring rates in Nigeria?
With Credit Direct Business, Invoice Discounting amounts from ₦500,000 to ₦20,000,000. Rates vary by provider, so always compare the total cost, not just the headline number.
Do I need collateral to finance an invoice?
No. An accepted invoice and a buyer domiciliation letter take the place of traditional collateral.
Can a manufacturer on a 90-day payment term qualify?
Yes. This facility exists specifically for businesses working with buyers on extended payment terms; manufacturers and B2B suppliers included.
Stop Waiting on Someone Else's Payment Schedule
A 90-day payment term is your buyer's schedule, not a rule you have to accept. If your next invoice is sitting unpaid while your costs are already due, that cash gap has a straightforward fix.
Get an Invoice Discounting quote today, and turn your next accepted invoice into working capital instead of a waiting game. For a full breakdown of every loan type available to Nigerian SMEs, see our complete guide to business loans in Nigeria.