
Before you pick a phone, the first number you actually need is your down payment. It's the one figure that decides whether a phone is within reach right now or something you'll need to save toward a little longer, and it's worth understanding before you fall in love with a device you can’t afford yet.
Here's how down payments work on instalment plans, how much you should pay upfront, and how to work out your own number for any phone you're considering.
What a Down Payment Actually Does
A down payment isn't just a formality. Let’s rephrase it as a commitment to completing repayment plan and, in general lending, can even work in the buyer's favour by improving the terms they're offered. The core idea holds across any instalment arrangement, phones included.
Credit Direct Checkout's Down Payment Structure
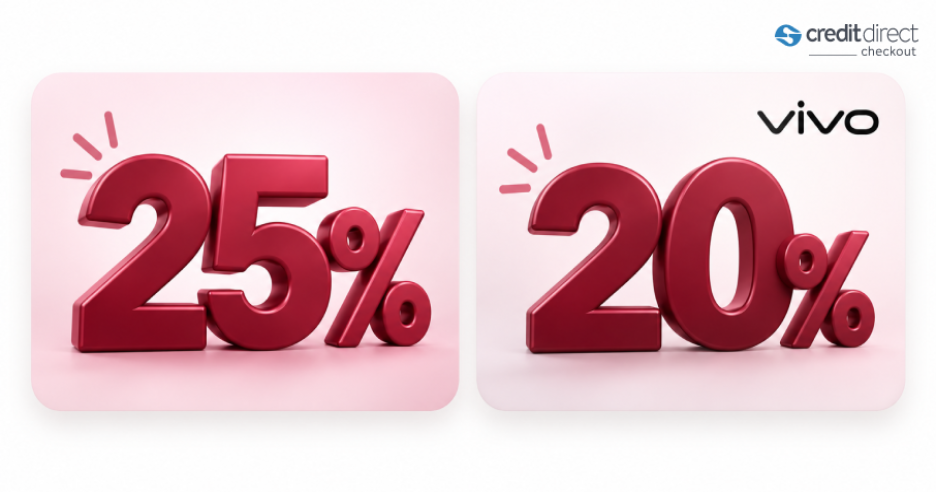
On Credit Direct Checkout, the standard minimum down payment is 25% of the phone's price, with the remaining 75% split across 6 monthly instalments. This applies across most phones on the platform, from budget Androids to flagship iPhones.
There's one notable exception. Phones from vivo carry a discounted 20% minimum down payment instead of the standard 25%, under an official partnership between Credit Direct and vivo. If you're weighing a vivo phone against other brands, that lower deposit is worth factoring into your decision. See our Vivo price and instalment guide for the full breakdown.
How to Calculate Your Down Payment
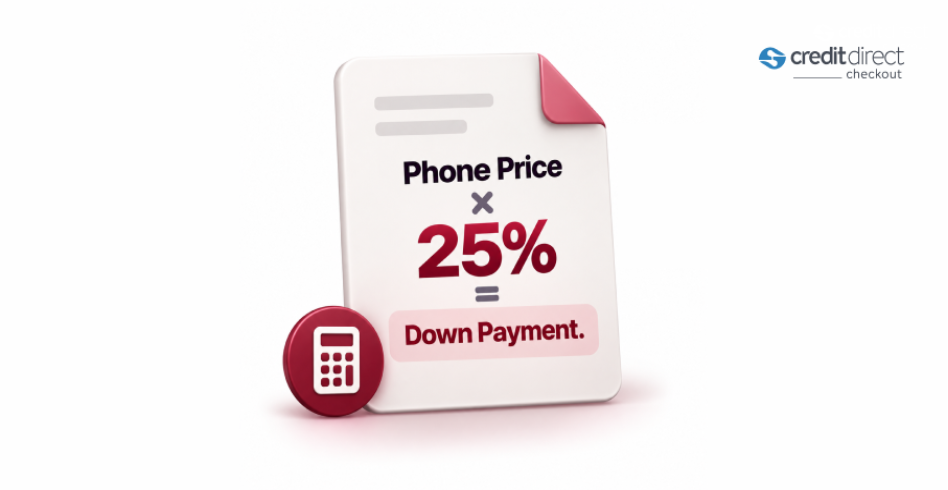
The formula is straightforward:
Down payment = Phone price × Deposit percentage (25%, or 20% for vivo)
Here's what that looks like for a few real phone prices:
Once you've worked out the down payment, the balance splits evenly across 6 monthly instalments. For example, on the Samsung Galaxy A07 above, the remaining ₦123,360 splits into 6 monthly payments of ₦20,560 each. It is worthy of note that these pricing varies across merchants, and excludes management fees.
What Can Change the Amount You Pay
A few things affect the exact figure you'll see:
The phone's price. A higher-priced phone means a higher down payment in naira terms, even though the percentage stays the same. A ₦700,000 phone at 25% requires ₦175,000 upfront, compared to ₦41,120 for a ₦164,480 phone.
The brand. As covered above, vivo's 20% rate is currently the one exception to Checkout's standard 25%.
Your approved limit. The Your Know Your Limit feature on our website shows you how much shopping credit you're approved for in total, which in turn affects which phones and price ranges are realistically within your down payment budget.
Budgeting for Your Down Payment
If you're working toward a specific phone, it helps to know your target number in advance rather than discovering it at checkout. Browsing our best budget Android phones under 200k guide is a good way to see real prices and their corresponding down payments side by side before you commit to one. For the full process of buying any phone on instalment, from choosing a merchant to completing checkout, see our guide on how to buy any phone on instalment in Nigeria.
Know Your Limit Before You Calculate Anything Else
Credit approval is the first real step in the buying journey, before you even settle on a phone or a down payment figure. Knowing your limit tells you what you can realistically work with, so you're not calculating deposits for a phone that's out of reach.
The Know Your Limit feature on our website gives you your shopping credit in under 5 minutes, with no impact on your credit score. Check Your Limit Now and know your number before you start shopping.